Short & Sweet no. 8
Do not fall into the operator trap when flying within the EU and UK
What is the operator trap?
Get things right from the get-go
What are the pitfalls?
We recommend these aircraft registrations
What is the only option?
 We often receive an inquiry sounding something like this: “We just brought a new aircraft into our operation and will be flying to Europe. Please tell us how to do so properly”.
Behind this inquiry is often an operating company that have new clients as well as private and corporate operators where the aircraft ownership structure makes it difficult to operate the aircraft within Europe in accordance with the various customs regulations without vast consequences due to the aircraft ownership, operatorship, aircraft registration, and operating structure that does not fit into either of the two customs entry options, namely the Temporary Admission or full importation procedure.
We call the above situation the “operator trap” because reasonable solutions are sometimes simply not available. Our goal is to point out that the aircraft ownership, operatorship, aircraft registration, and operating structure are very important aspects to consider if an operator is planning to fly as a guest or eventually base an aircraft within the EU or the UK.
A quick background of the customs regulation
Any aircraft flying into the EU or the UK will fly under customs control using either Temporary Admission or full importation. There are no other options. The Temporary Admission procedure can only be used by EU or UK outsiders where the aircraft is owned (including any UBOs), operated, registered, and based outside the EU or the UK, leaving EU or UK insiders with only one option – full importation with a payment of all taxes.
What are the pitfalls?
Please be aware that the setups described below can create an operator trap. If an owner or operator recognizes their setup in one or more of the points listed below, the alarm bell should ring, and the owner or operator might consider restructuring the setup before it is too late. Please remember that the list is not comprehensive and that the full importation and Temporary Admission procedures also have other preconditions and limitations that must be followed continuously.
 No-gos for a full importation (Both EU + UK):
- The owner or importing entity is a shell company
- The owner or importing entity is incorporated or domiciled in exotic places or jurisdictions known as tax havens
- The owner or importing entity is not using the aircraft 100% in their pursuit of real economic activity *)
- The aircraft is not commercially operated
- Some business activities, such as selected real estate activities, banking and finance, insurance, gaming, and holding companies, etc., are not subject to VAT, meaning that an importing entity with such activities cannot deduct the imposed import VAT during a full importation even though the aircraft is used 100% for real business activities within the mentioned areas
 No-gos for Temporary Admission (EU):
- The owner entity is incorporated or domiciled within the EU
- Any potential lessee is incorporated or domiciled within the EU
- Any potential UBO or main user has habitual residence within the EU
- The physical operator is incorporated or domiciled within the EU
- The aircraft registration has origin within the EU *) **)
- A San Marino (T7) registration will work fine. San Marino is outside the EU (customs territory of the Union)
- A Gibraltar (ZD or VP-G) registration will work fine. Gibraltar is outside the EU (customs territory of the Union)
 No-gos for Temporary Admission (UK):
- The owner entity is incorporated or domiciled within the UK, including the Isle of Man *)
- Any potential lessee is incorporated or domiciled within the UK, including the Isle of Man
- Any potential UBO or main user has habitual residence within the UK, including the Isle of Man
- The physical operator is incorporated or domiciled within the UK, including the Isle of Man
- The aircraft registration has origin within the UK, including the Isle of Man **)
- The Isle of Man is inside the customs territory of the UK
- An Isle of Man registration will not work
Please see more about aircraft registrations here.
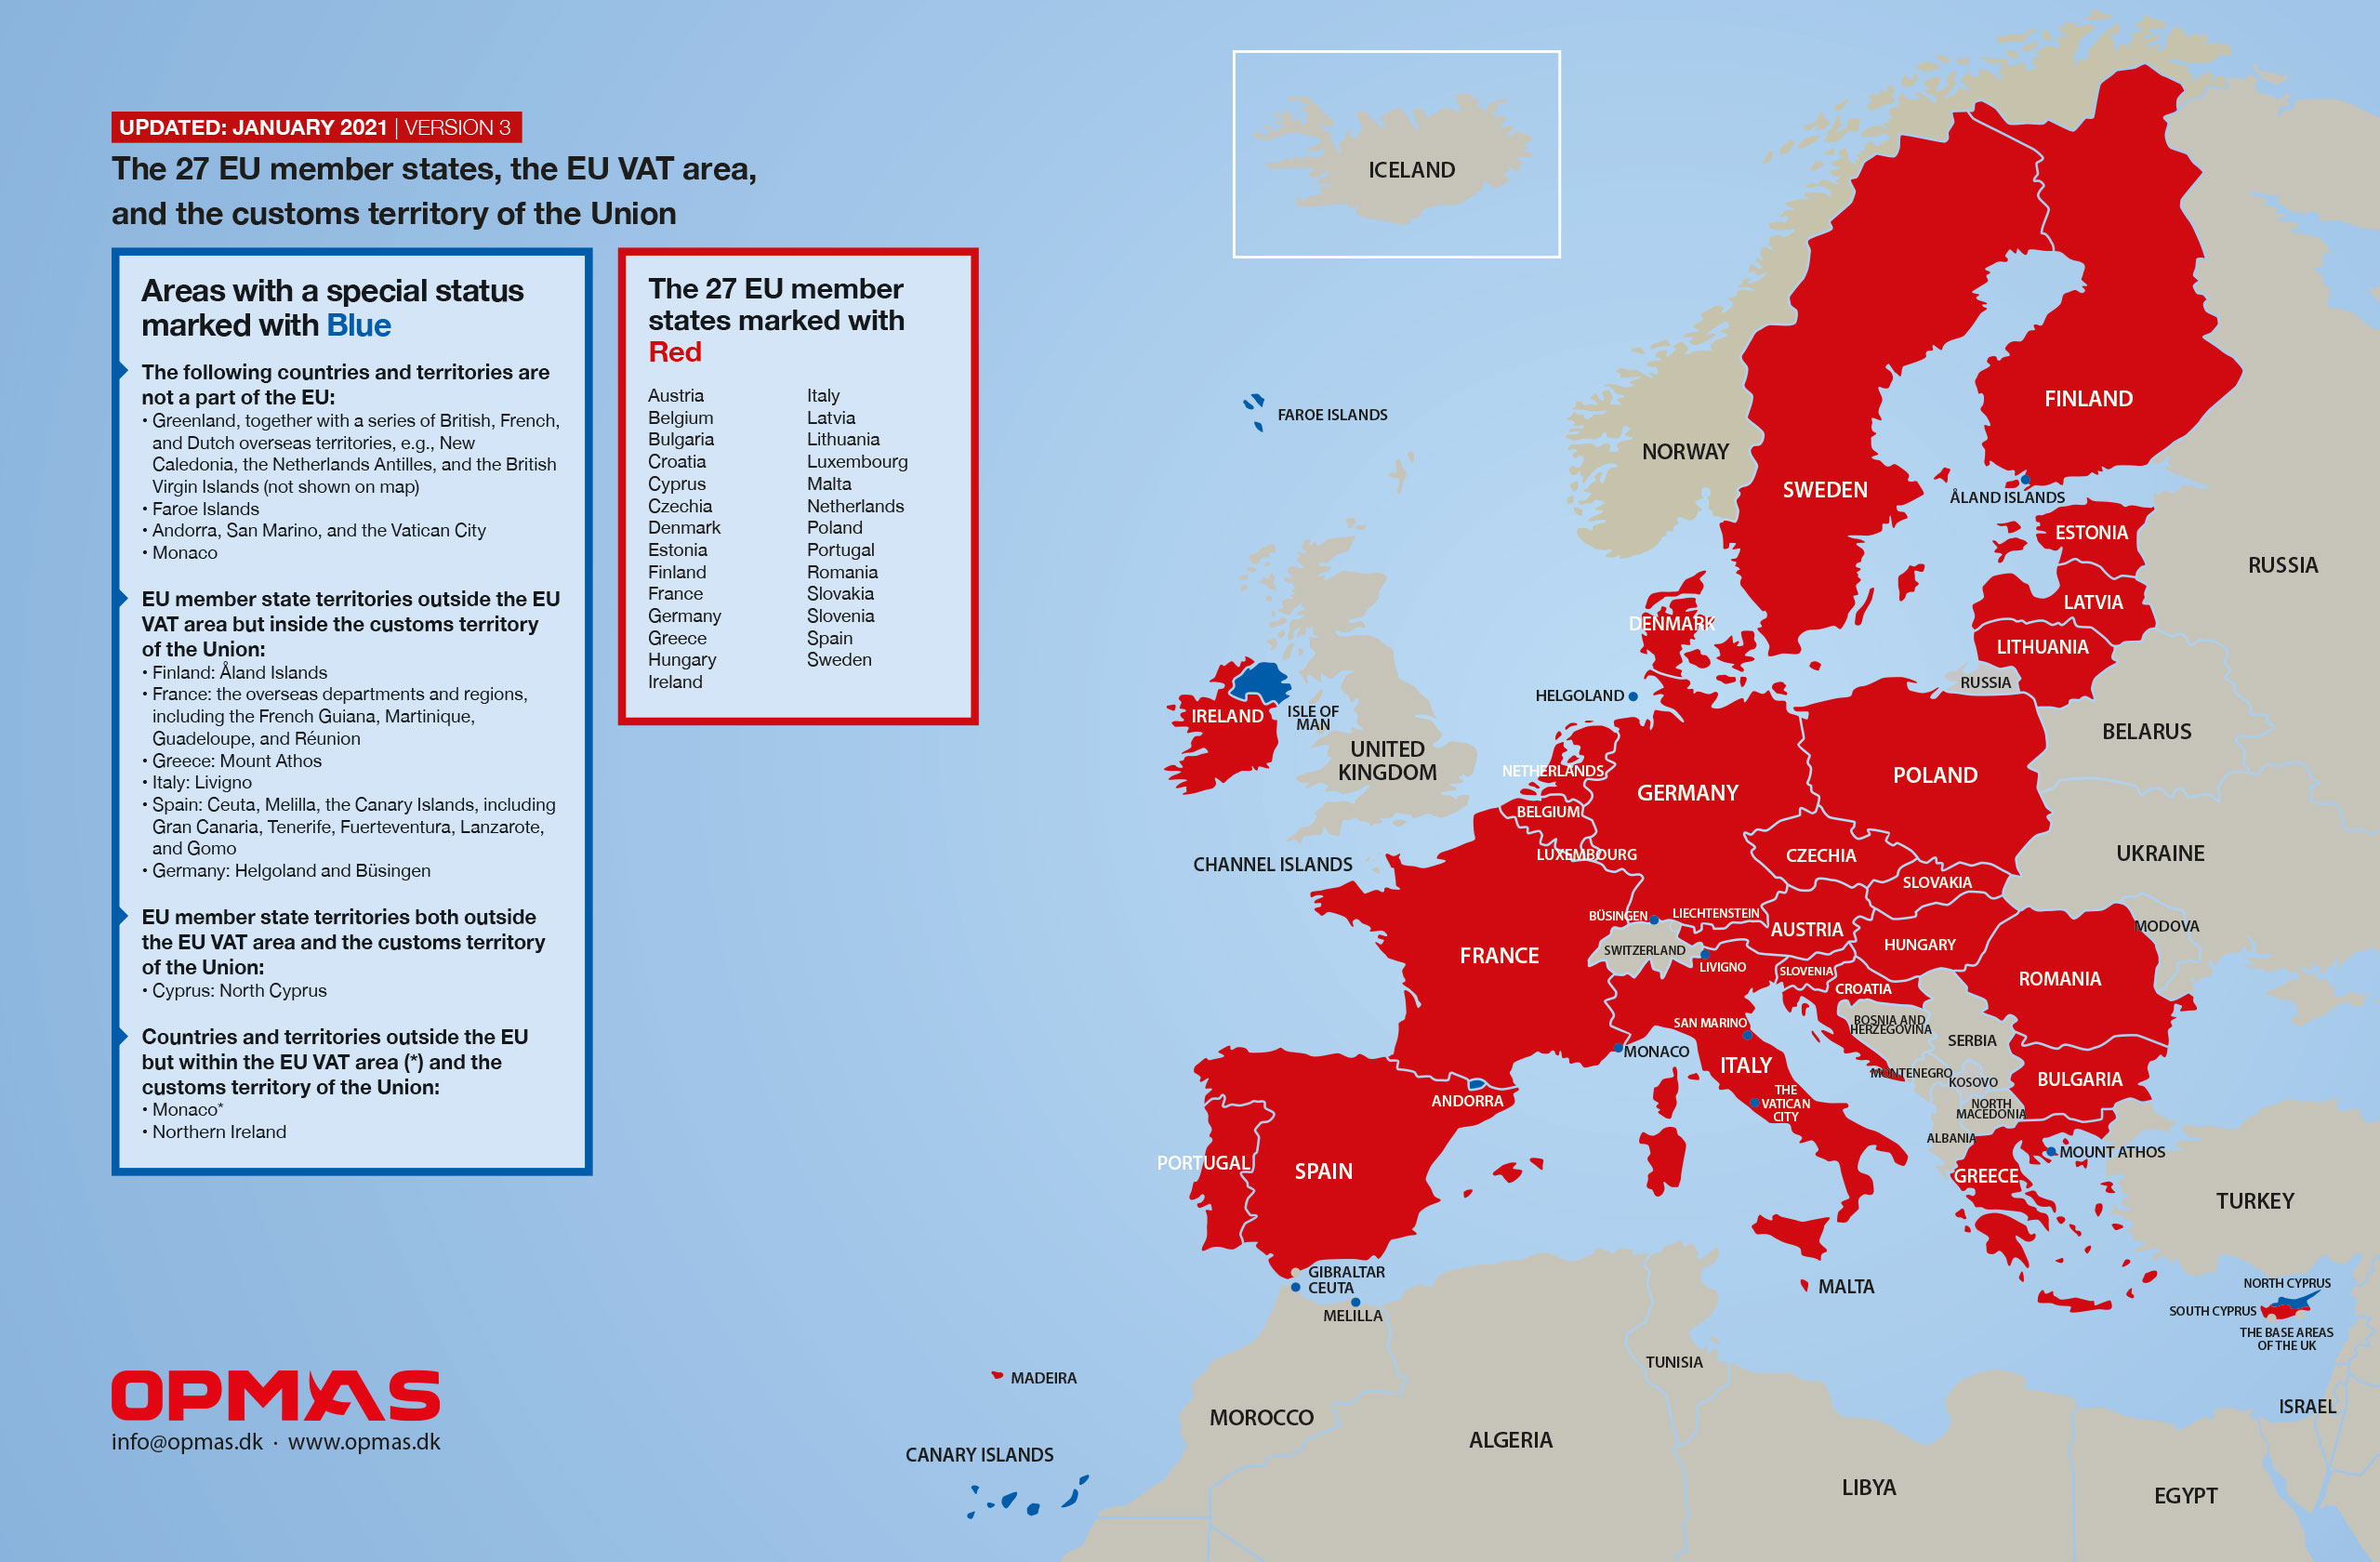
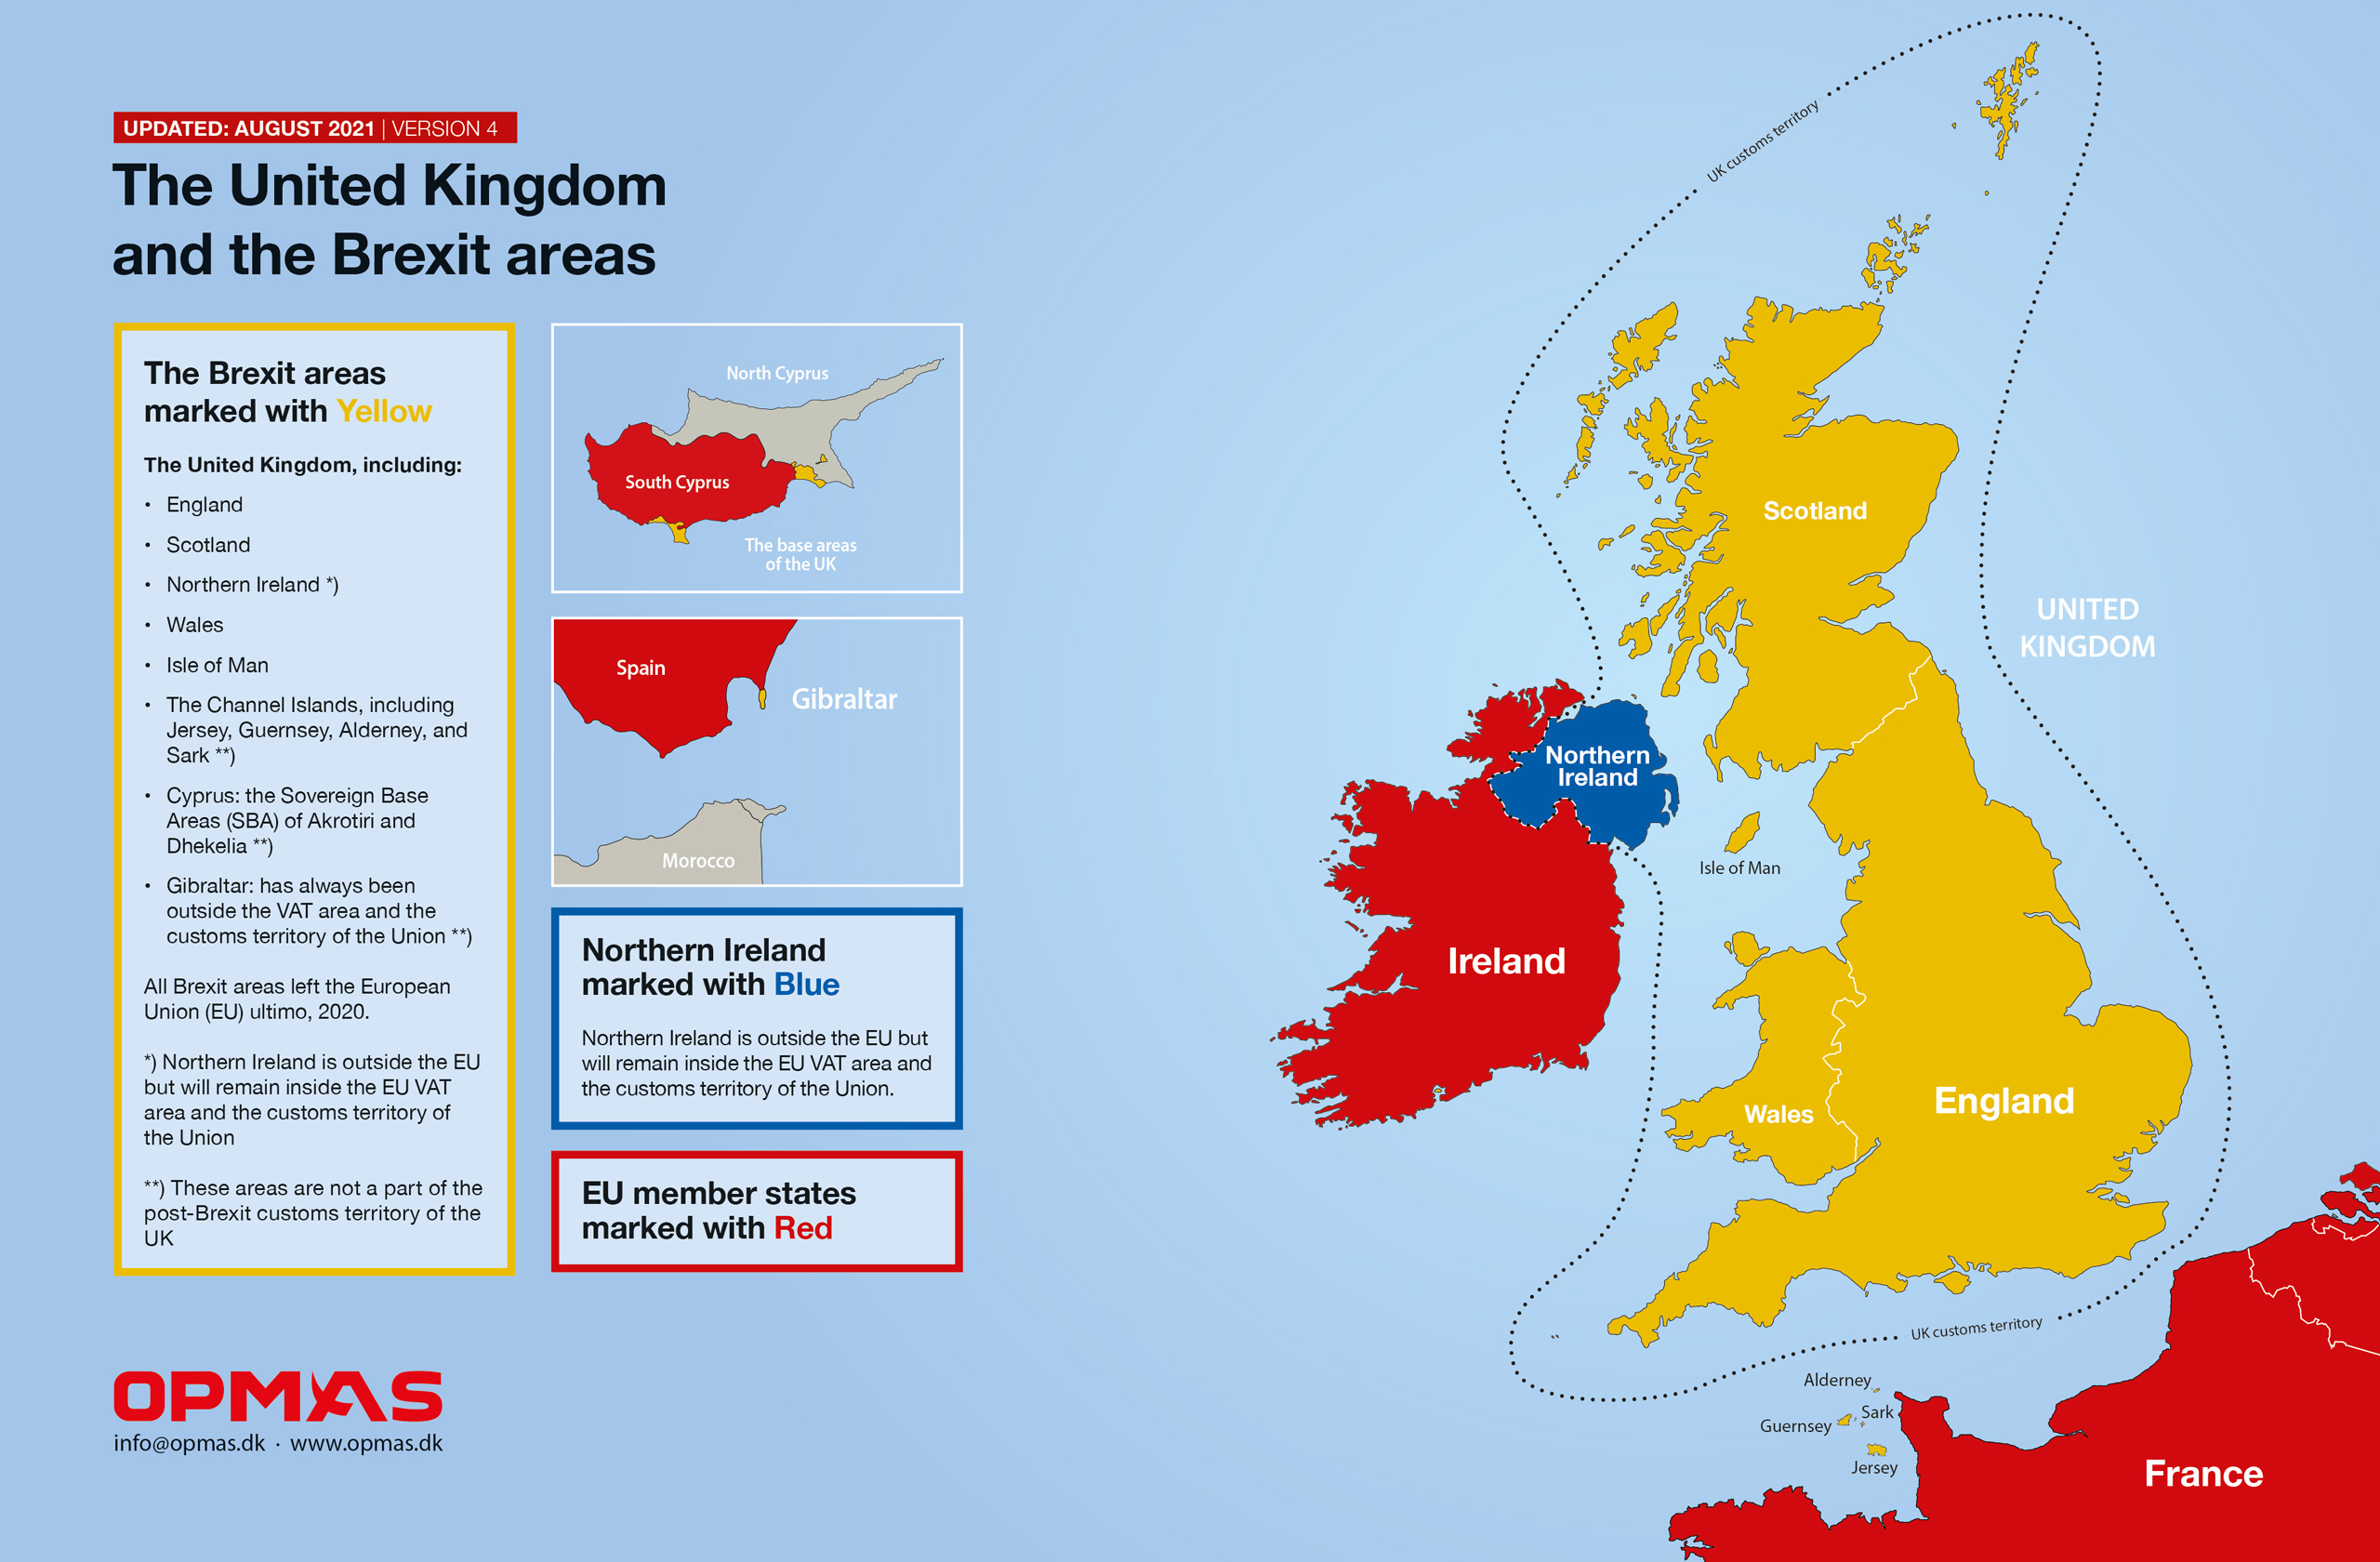
OPMAS has earlier made overview maps of the customs territory of the Union (EU) and the UK customs territory. And, just for the record, Jersey and Guernsey are not a part of the latter.
The only option left
If the aircraft will fly to the EU or the UK and not adapt the above recommendations, the only option left to fly legally would be to pay the local VAT, ranging from 17 to 27% within the EU and 20% in the UK. The amount is based on the current aircraft value.
Such a VAT payment could also be the tragic result if local customs find an aircraft non-compliant with Temporary Admission during ramp checks at both places. In addition, there is a risk that any eventual VAT payment would include customs duty and a fine.
How can we help?
If you have questions about the above, please do not hesitate to contact us.
List of all OPMAS
Short & Sweet mails:
No. 26 – Understanding Temporary Admission – Explained in a Different Way
Aug 2026 TA
No. 25 – Which types of specialized operations cannot be performed under Temporary Admission?
Jan 2026 TA
No. 24 – Can the Customs Warehouse procedure be used to close a deal?
Feb 2025 TA FI
No. 23 – Temporary Admission is supposed to be paperless, so why is documentation needed?
Oct 2024 TA
No. 22 – What does it take to be compliant?
Jun 2024 TA FI
No. 21 – Part 4: Using Temporary Admission – How, when, and why? Be prepared for a customs ramp check
Jan 2024 – Updated 2026 TA
No. 20 – Buying or selling aircraft within, to, or from the EU
Nov 2023 TA FI
No. 19 – The real differences between full importation and Temporary Admission
Sep 2023 - Updated 2026 TA FI
No. 18 – Exporting an aircraft from the EU
Jun 2023 - Updated 2024 FI
No. 17 – What is the correct use of a corporate aircraft?
Mar 2023 - Updated 2024 FI
No. 16 – Which customs procedures can be used for parking an aircraft within the EU?
Jan 2023 - Updated 2024 TA FI
No. 15 – Liability and risk elements associated with EU importation and admission
Oct 2022 - Updated 2024 TA FI
No. 14 – Part 3: Using Temporary Admission – when does an operator need help?
Aug 2022 – Updated 2026 TA
No. 13 – Importation impacts when traveling the world in corporate aircraft
Jun 2022 - Updated 2024 FI
No. 12 – How to get the 0% airline VAT exemption meant for commercial operators
May 2022 - Updated 2024 FI
No. 11 – Part 2: Using Temporary Admission – what do customs look for during a ramp check, and why?
Mar 2022 – Updated 2026 TA
No. 10 – How to handle aircraft maintenance correct in a customs context
Feb 2022 - Updated 2024 TA FI
No. 9 – Part 1: Using Temporary Admission – the Supporting Document
Dec 2021 – Updated 2026 TA
No. 8 – Do not fall into the operator trap when flying within the EU and UK
Oct 2021 - Updated 2026 TA FI
No. 7 – Which aircraft registrations can be used with Temporary Admission when flying to the EU or UK?
Sep 2021 - Updated 2026 TA
No. 6 – Flying with EU-resident persons onboard when using Temporary Admission
Aug 2021 - Updated 2026 TA
No. 5 – What about private use of corporate aircraft?
May 2021 - Updated 2025 TA FI
No. 4 – What does ‘VAT paid’ mean?
Mar 2021 - Updated 2024 FI
No. 3 – Is a full importation needed in both the UK and the EU27?
Mar 2021 - Updated 2024 FI
No. 2 – Flying commercially within the EU
Feb 2021 - Updated 2025 TA FI
No. 1 – Flying with the CEO
Nov 2020 - Updated 2025 TA FI