Short & Sweet no. 7
Which aircraft registrations can be used with Temporary Admission when flying to the EU or UK?
- Chose the right registration to fly freely
- Where are the pitfalls?
- You might not want to use an Isle of Man (M) registration
 We are often asked which aircraft registrations can be used with Temporary Admission (TA) when an aircraft is being used within both the EU and UK by an owner and/or by an operator that resides outside these areas.
Background: the customs aspect of flying within the EU
Any aircraft flying into the EU will fly under customs control using either TA or full importation. There are no other options. If the aircraft is not already fully imported, the aircraft will automatically be considered as flying under TA even though the owner or operator has not themselves taken any action to activate this procedure or realized that their aircraft is flying under TA. The TA procedure is thus always required for non-EU imported aircraft, even for flights with only one stop within the EU. Here, non-compliance with TA will most likely activate a direct payment of the importation taxes for the owner or operator, VAT ranging from 17-27% and customs duty ranging from 2.7-7.7. The TA procedure can only be used by EU outsiders where the aircraft is owned (including any UBOs), operated, registered, and based outside the EU, leaving EU insiders only one option: full importation. EU outsiders can, of course, choose to use full importation instead of TA if they find it beneficial. Both options can be used commercially, corporately, or privately if applied correctly.
Most aircraft registrations can be used without problems
Most of the popular aircraft registrations can be used with a few exceptions. Please have a look at the table below. Note that that none of the 27 EU aircraft registration can of course be used with TA when flying within the EU. Please be aware that full TA compliance also includes correct handling of various limitations and situations, which is why a compliance test is fundamental before flying to the EU.
| Jurisdiction |  |  |
 Aruba (P4) |  | |
 Bahamas (VP-B) | | |
 Bermuda (VP-B or VQ-B) | | |
 Cayman Islands (VP-C) | | |
 Cyprus (5B) * |  | |
 Gibraltar (ZD) **** | | |
 Guernsey (2) ** | | |
 Ireland (EI) * | | |
 Isle of Man (M) *** | | |
 Jersey (ZJ) ** | | |
 Malta (9H) * | | |
 San Marino (T7) **** | | |
 Switzerland (HB) | | |
| United Kingdom (G) | | |
 USA (N) | | |
* Cyprus, Ireland, and Malta are all inside 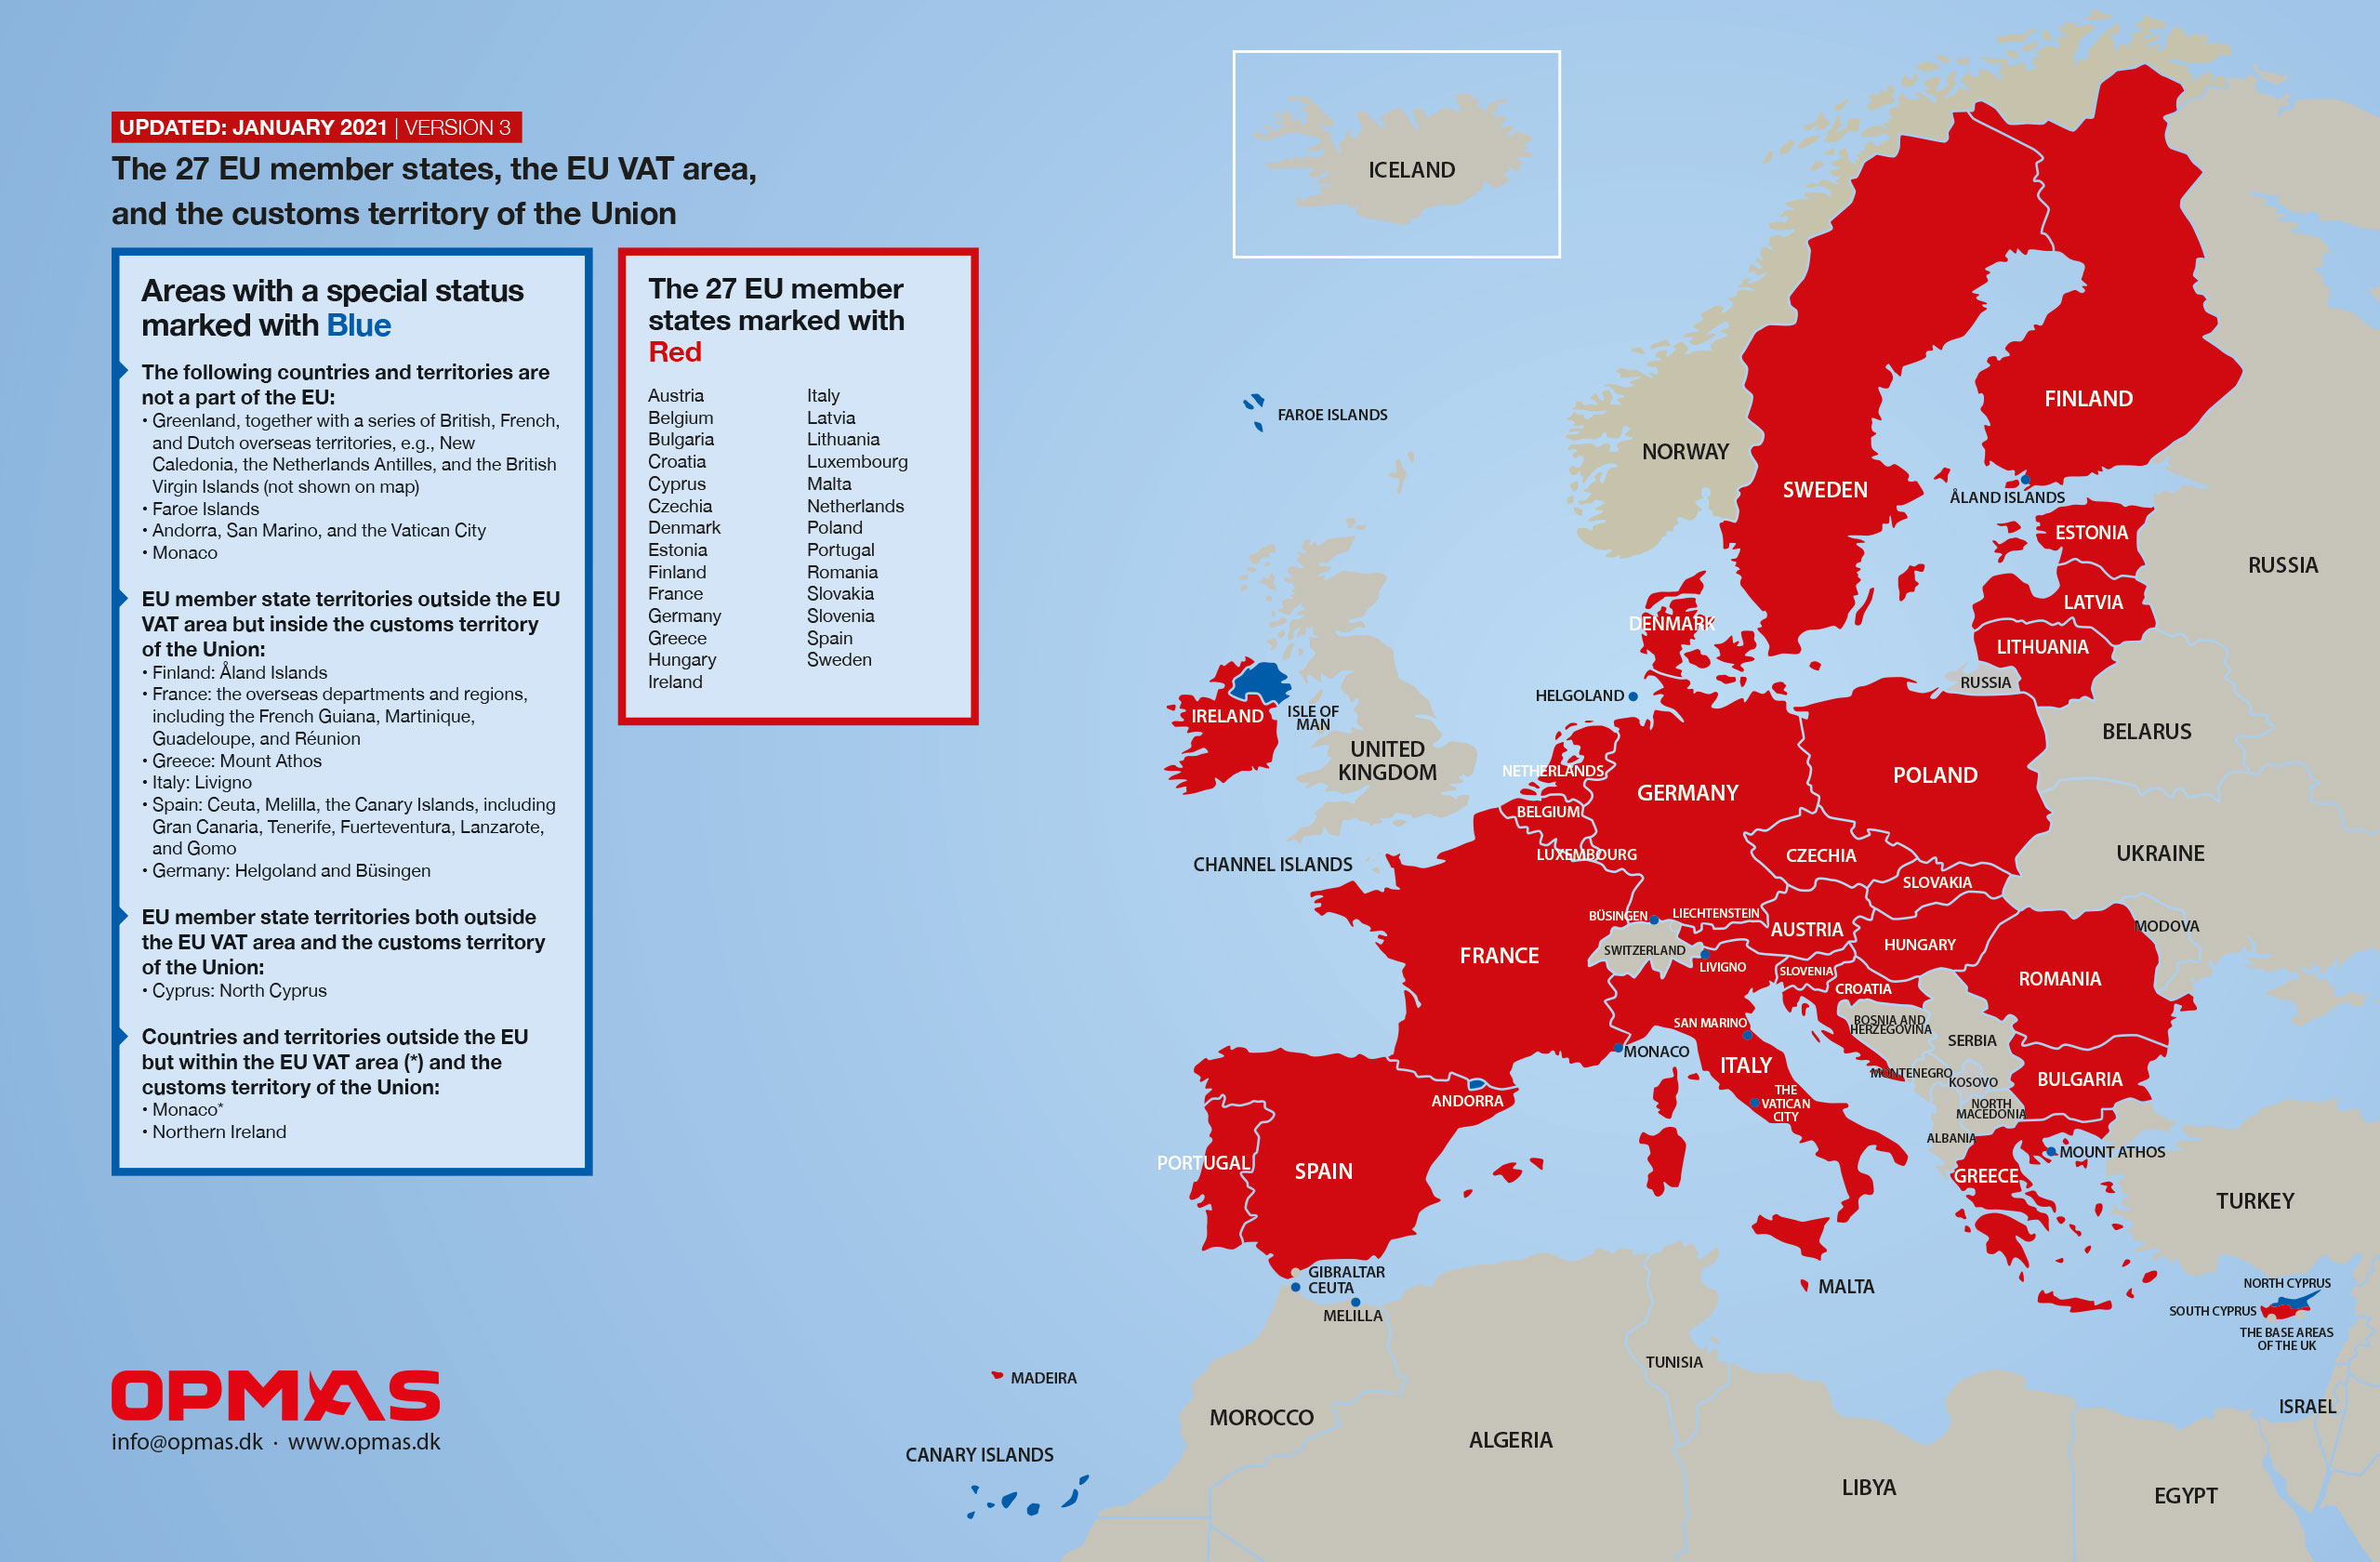
** The Channel Islands are all outside 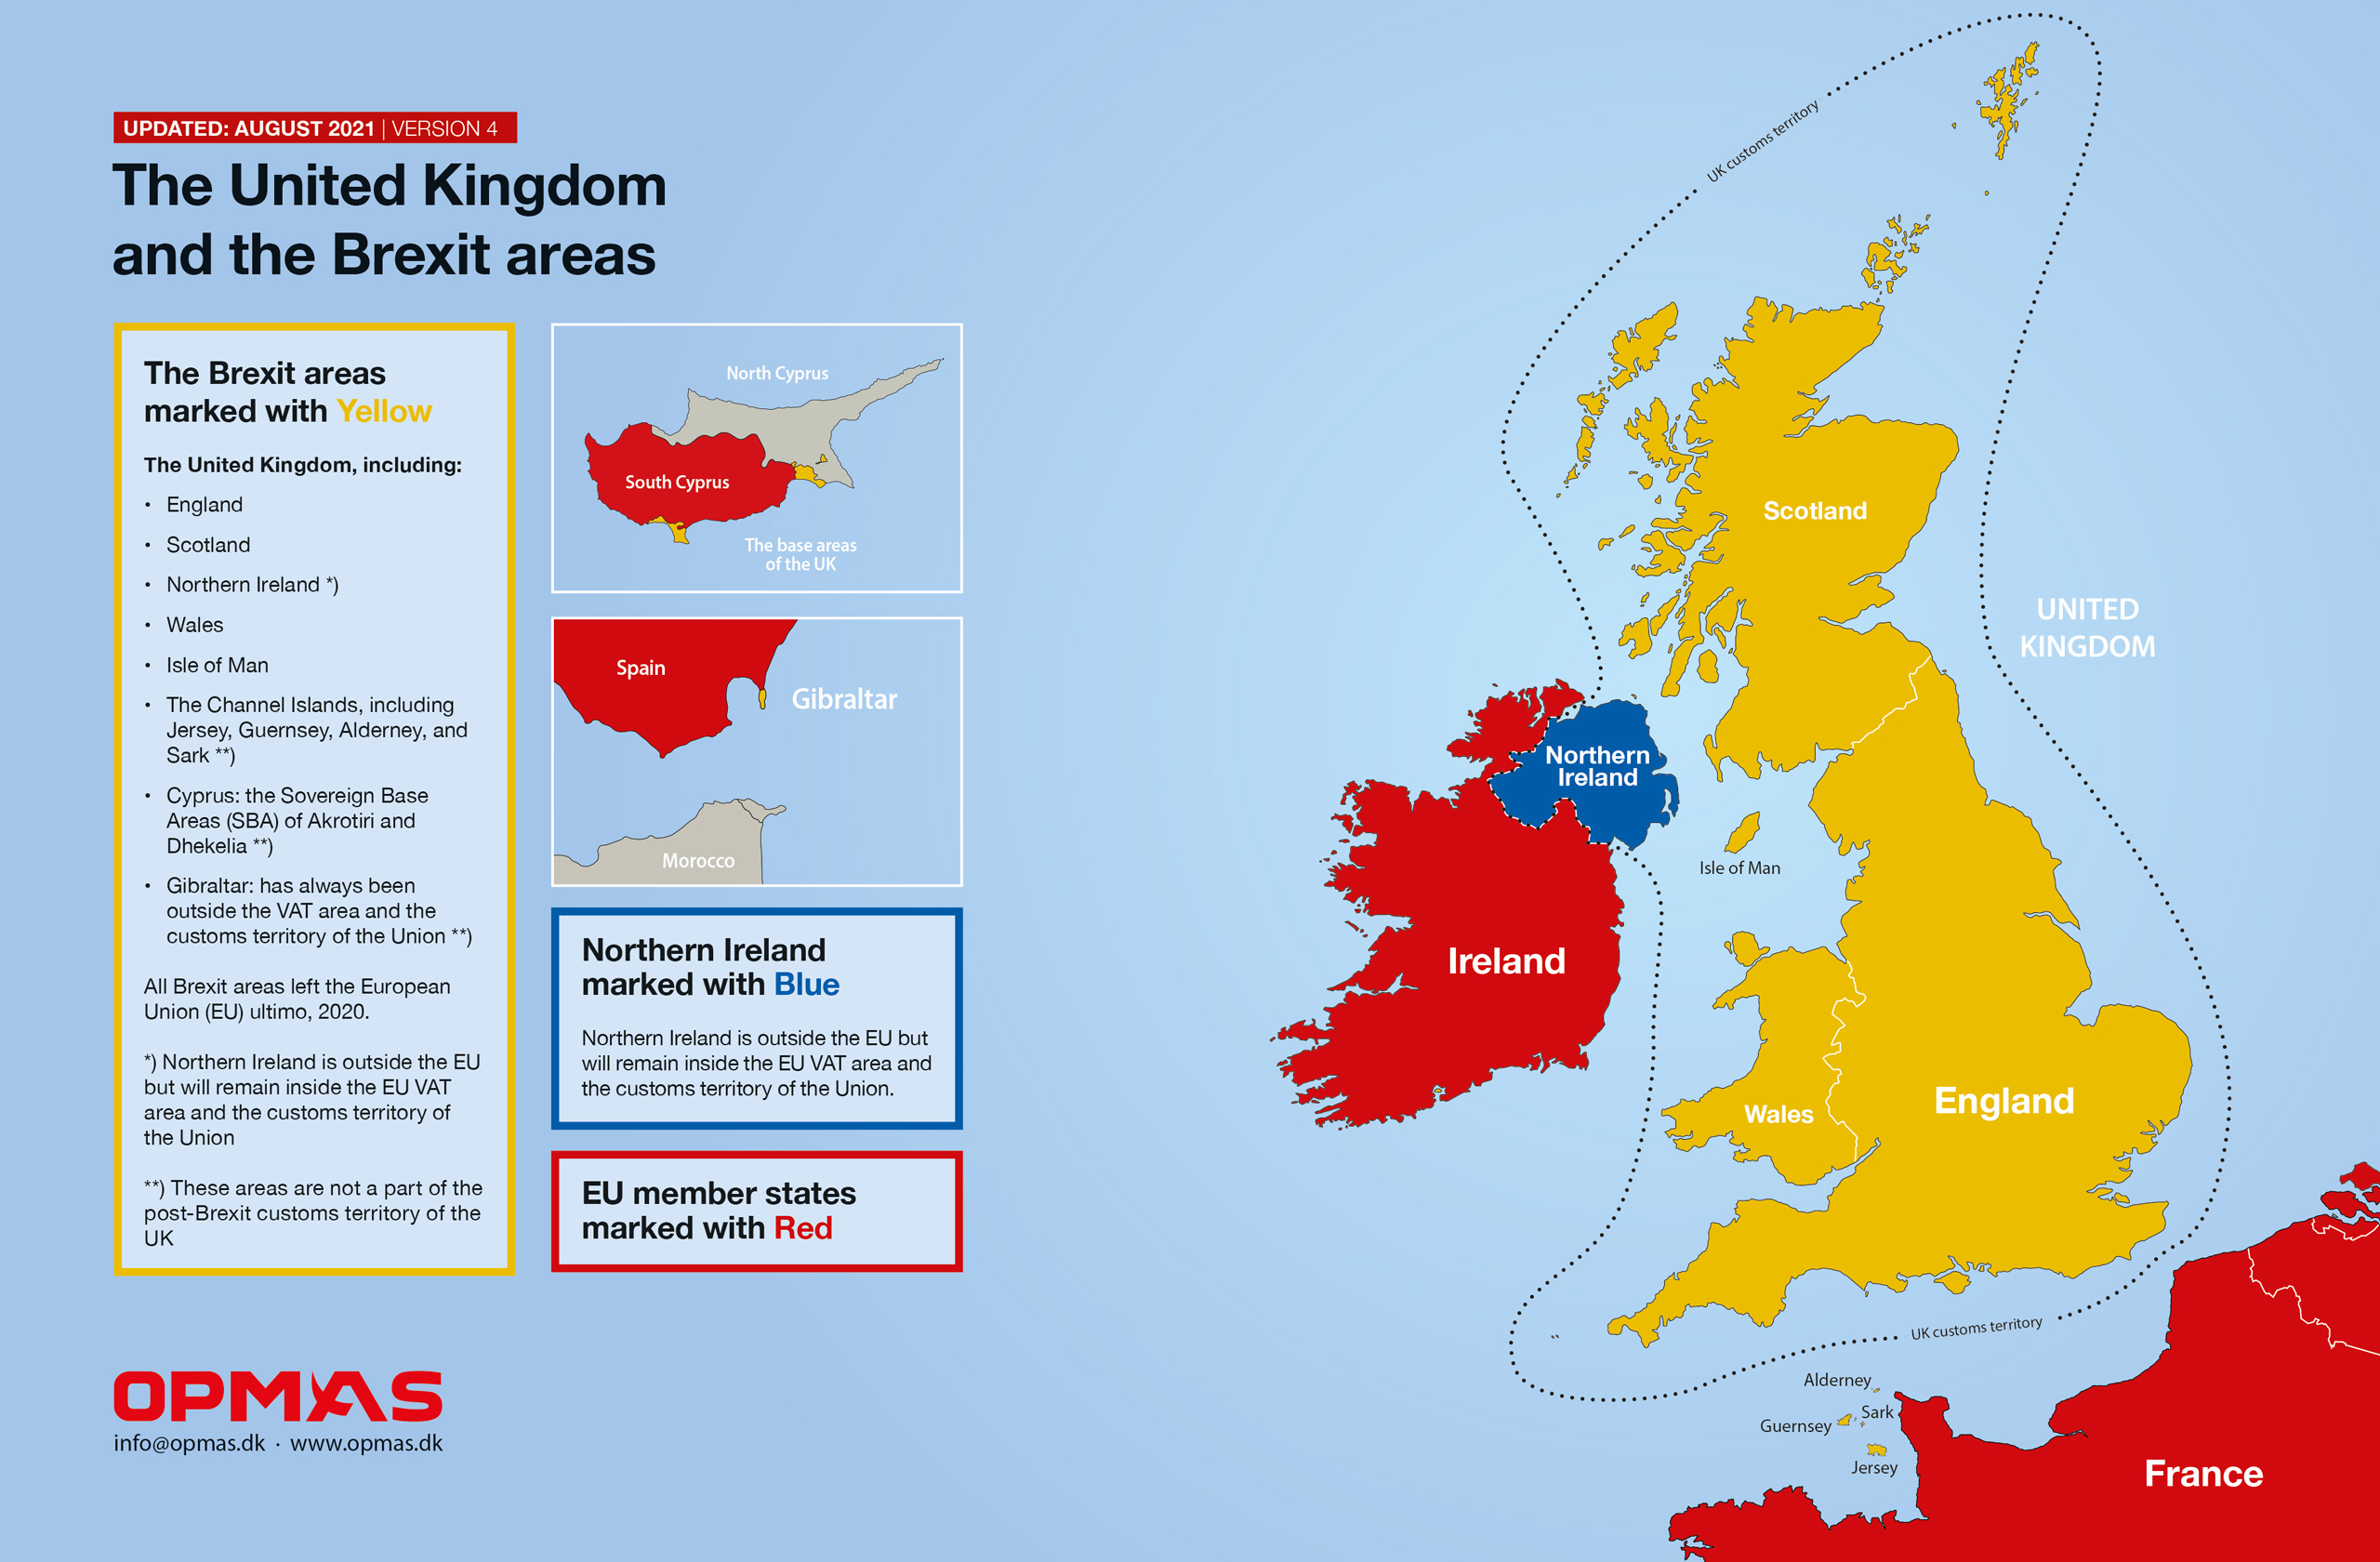
*** The Isle of Man is inside
**** Both San Marino and Gibraltar are outside
You might not want to use the Isle of Man (M) registration
It is perfectly fine to use the M-registration or an Isle of Man entity as the owner or operator when flying within the EU, if the total setup meets the requirements for the TA procedure. However, the same setup may create vast problems if flying to the UK. As we anticipate most aircraft will eventually fly to the UK, or that every owner, at least, wishes to have the possibility, we suggest not using an Isle of Man owner entity or M-registration.
This is because an Isle of Man connection means that the aircraft cannot use the TA procedure when flying to the UK, leaving a full UK importation as the only option. In many ways, the HMRC (British customs) has limited the access to aircraft importations for foreign entities unless the imposed VAT (20% of the aircraft’s value) is fully paid without the possibility of reclaiming. The risk is that the aircraft will be impounded by the HMRC.
Our argument is that nobody should use an inflexible aircraft registration or take on extra tax liabilities in another jurisdiction by initiating a full UK importation. Especially as other options for flying to UK exist by merely using one of the aircraft registrations listed on the positive list above.
How can we help?
If you have questions about the above, please do not hesitate to contact us.
List of all OPMAS
Short & Sweet mails:
No. 26 – Understanding Temporary Admission – Explained in a Different Way
Aug 2026 TA
No. 25 – Which types of specialized operations cannot be performed under Temporary Admission?
Jan 2026 TA
No. 24 – Can the Customs Warehouse procedure be used to close a deal?
Feb 2025 TA FI
No. 23 – Temporary Admission is supposed to be paperless, so why is documentation needed?
Oct 2024 TA
No. 22 – What does it take to be compliant?
Jun 2024 TA FI
No. 21 – Part 4: Using Temporary Admission – How, when, and why? Be prepared for a customs ramp check
Jan 2024 – Updated 2026 TA
No. 20 – Buying or selling aircraft within, to, or from the EU
Nov 2023 TA FI
No. 19 – The real differences between full importation and Temporary Admission
Sep 2023 - Updated 2026 TA FI
No. 18 – Exporting an aircraft from the EU
Jun 2023 - Updated 2024 FI
No. 17 – What is the correct use of a corporate aircraft?
Mar 2023 - Updated 2024 FI
No. 16 – Which customs procedures can be used for parking an aircraft within the EU?
Jan 2023 - Updated 2024 TA FI
No. 15 – Liability and risk elements associated with EU importation and admission
Oct 2022 - Updated 2024 TA FI
No. 14 – Part 3: Using Temporary Admission – when does an operator need help?
Aug 2022 – Updated 2026 TA
No. 13 – Importation impacts when traveling the world in corporate aircraft
Jun 2022 - Updated 2024 FI
No. 12 – How to get the 0% airline VAT exemption meant for commercial operators
May 2022 - Updated 2024 FI
No. 11 – Part 2: Using Temporary Admission – what do customs look for during a ramp check, and why?
Mar 2022 – Updated 2026 TA
No. 10 – How to handle aircraft maintenance correct in a customs context
Feb 2022 - Updated 2024 TA FI
No. 9 – Part 1: Using Temporary Admission – the Supporting Document
Dec 2021 – Updated 2026 TA
No. 8 – Do not fall into the operator trap when flying within the EU and UK
Oct 2021 - Updated 2024 TA FI
No. 7 – Which aircraft registrations can be used with Temporary Admission when flying to the EU or UK?
Sep 2021 - Updated 2026 TA
No. 6 – Flying with EU-resident persons onboard when using Temporary Admission
Aug 2021 - Updated 2026 TA
No. 5 – What about private use of corporate aircraft?
May 2021 - Updated 2025 TA FI
No. 4 – What does ‘VAT paid’ mean?
Mar 2021 - Updated 2024 FI
No. 3 – Is a full importation needed in both the UK and the EU27?
Mar 2021 - Updated 2024 FI
No. 2 – Flying commercially within the EU
Feb 2021 - Updated 2025 TA FI
No. 1 – Flying with the CEO
Nov 2020 - Updated 2025 TA FI
OPMAS ApS
Soenderborggade 9
DK-8000 Aarhus C
Denmark
Tel: +45 70 20 00 51
Email: info@opmas.dk
Go to contact page
Join our mailing list and receive
the latest news and updates
from the OPMAS team.
Follow Us on LinkedIn
Visit our LinkedIn page – get important news about EU importation and admission issues for aircraft owners and operators.
Design by www.himmelblaa.dk